8 Contractor Insurance Gaps to Close Before Year End
Quick answer: The insurance gaps that bite contractors at year end are usually ones nobody checked: a wire sent to a fake supplier email that your general liability won't cover, rented equipment your policy may not cover, a builders risk policy nobody bought, a layoff that turns into a claim, a driver your carrier won't accept at renewal, a contract that asks for higher limits than you carry, bonding capacity that depends on this year's books, and payroll records that decide what your workers comp audit charges. Each one has a simple check you can do before January.
Key takeaways:
- General liability won't touch a wire sent to a fake supplier email. A lot of cyber policies won't either unless they include social engineering or funds transfer fraud coverage.
- Rental contracts usually make you responsible for the equipment until it comes back. Rented equipment coverage is usually added to your inland marine policy.
- Your general liability usually doesn't cover the building under construction. That's builders risk, and the contract decides who buys it.
- Discrimination, retaliation and wrongful termination claims need employment practices liability (EPLI), not general liability or workers comp.
- Commercial auto carriers commonly check your drivers' records at the start and again at renewal.
- An umbrella sits on top of your liability and auto policies, but some have their own exclusions.
- Your surety bases a lot of your bonding capacity on your financial statements and work-in-progress schedule.
Does Business Insurance Cover a Wire Sent to a Fake Supplier Email?
The email looked like your supplier: new bank account, please wire it there. The money's gone. Contractors get hit with this because you move big payments by email, and year end is chaos.
Your general liability won't touch it. A lot of cyber policies won't either, unless they include social engineering or funds transfer fraud coverage, sometimes with a smaller limit than the rest of the policy.
The fix is mostly habit. Any time a vendor's bank info changes, call them at a number you already have, not the one in the email, and make your office manager do the same. Then ask your agent what your policy does if a wire goes to the wrong place.
Does Contractor Insurance Cover Rented Equipment That Gets Stolen?
You rented a lift for the winter job, and it got stolen off the site over a weekend. The rental company handed you a contract that says you're responsible for that equipment until it comes back: damage, theft, all of it.
Your general liability doesn't cover equipment in your care. And the damage waiver the rental counter sells usually has holes in it, like theft from an unlocked site. That's what rented equipment coverage is for, usually added to your inland marine policy.
So before you rent, check whether your policy covers rented equipment, how much, and for how long. Then decide on the waiver at the counter.
Who Pays for Builders Risk Insurance on a Construction Job?
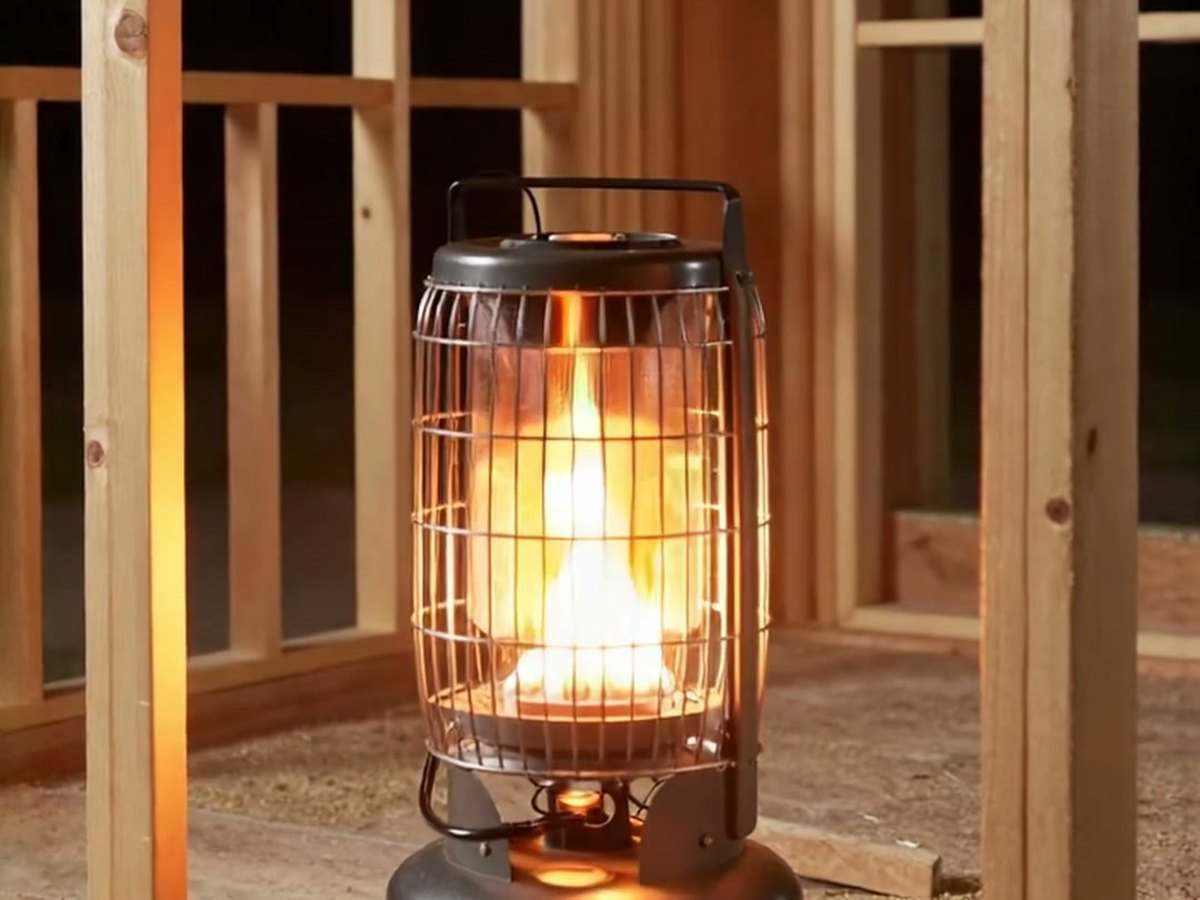
A space heater tips over in a framed-up house in January. Whose policy rebuilds it?
On a job under construction, the building itself usually isn't covered by your general liability. That's builders risk. The contract decides who buys it, the owner or you. If it says you, and you assumed the owner had it, that fire is yours to pay for.
Winter adds its own trouble, like temporary heat and materials sitting on an empty site. So read the insurance section to see who carries builders risk, make sure the policy starts when materials arrive, and ask your agent how it handles theft and temporary heat.
Does My Business Insurance Cover a Lawsuit From a Laid-Off Employee?
Slow season means letting people go, and winter is when a lot of contractors cut crews. Then the letter shows up in February. A former employee who feels singled out may claim discrimination, retaliation or wrongful termination.
Your general liability doesn't cover that, and neither does workers comp. That takes employment practices liability, sometimes called EPLI. Even a claim with nothing to it costs money to defend.
So before layoffs, write down the reason, apply it the same way to everybody, and keep the paperwork. And ask your agent whether EPLI is on your policy, and whether it covers the defense. This is general information, not legal advice; an employment attorney can tell you what applies to your situation.
Can My Commercial Auto Insurance Exclude a Driver After Renewal?
You hired a driver in October. At renewal, your carrier pulls his driving record and doesn't like it.
Most commercial auto carriers check your drivers' records when you start and again at renewal. A few tickets or one DUI can raise your rate, or the carrier may ask you to exclude that driver. Finding out in December is a hassle. Finding out after he wrecks your truck is a lot worse.
So send your agent a current driver list now, with license numbers and dates of birth, and include anybody who drives for you. And before you hand a new hire the keys, have his record checked first.
Do I Need an Umbrella Policy to Bid Commercial Construction Jobs?
You won the bigger job. Then the contract asked for higher limits than you currently carry. Commercial jobs come with bigger insurance requirements, and owners and developers write minimum limits right into the contract.
That's what an umbrella policy is for. It sits on top of your liability and auto policies and kicks in when their limits run out. But not every umbrella follows your underlying policies the same way. Some have their own exclusions, so the limit you're counting on may not apply to every claim.
So before you bid, pull the limits out of the bid documents, and get your umbrella quote while there's still time to add it. If you're running several jobs at once, it also helps to understand how GL aggregate limits work across multiple jobs, and to price insurance into your bid before you submit it.
How Do I Increase My Bonding Capacity for Next Year?
You want to bid bigger bonded jobs in 2027. Bonding capacity is how much work a surety will back you on, one job at a time and all your jobs together.
They base a lot of that on your financial statements and your work-in-progress schedule. A shoebox of receipts doesn't tell them much. Statements from a CPA who knows construction tell them a lot more.
Before you close the year, collect what customers owe you, clean up your books, and get your CPA on the calendar, because January fills up fast. If bonded work is in your 2027 plan, start that conversation this month.
Is Your Workers Comp Audit Charging Office Time at a Field Rate?
Workers comp is priced by class code, and field work costs a lot more than office work. If someone on your payroll splits time between the office and the field, how your records show those hours matters at audit, and so does how overtime appears in your payroll reports. The rules vary by state, so ask your agent how your audit will treat split jobs and overtime before December closes. For the subcontractor side of the audit, see why a workers comp audit charged you for your subs.
What Should You Check Before January 1?
Eight gaps, one review. If you haven't worked through last week's list yet, start with the year-end insurance checklist for contractors. Want a second set of eyes on your coverage? Book a free coverage review with Wayne: https://calendar.app.google/VAXw1WFmRwkG2zjS7
Every policy is different, and only your carrier decides what's covered. This is general information, not legal or coverage advice. Read your own policy and talk with a licensed agent about your situation. Illustrations in this post are AI-generated.
Disclaimer: This article is for educational purposes only and does not constitute legal, regulatory, or professional insurance advice. Coverage requirements and options vary by state and individual circumstance. Please consult with a licensed insurance professional before making any coverage decisions.
Have Questions?
Speak with a Licensed Agent
Our team is ready to help Louisiana residents and businesses find the right coverage. No obligation, no pressure.